A social media sentiment stock market API is not a feed of bullish and bearish posts. Used correctly, it is an attention-intelligence layer: a structured way to measure when a ticker’s conversation is accelerating, how the narrative is changing, and whether that shift has enough quality to deserve research time.
For active market participants and developers, the value is speed with context. Price and volume show that activity is happening. Social data can help explain where attention is forming before it becomes obvious on a chart. The catch is that raw chatter is noisy, easily distorted, and often disconnected from a real catalyst. A useful API must do far more than count mentions.
What a Social Media Sentiment Stock Market API Should Deliver
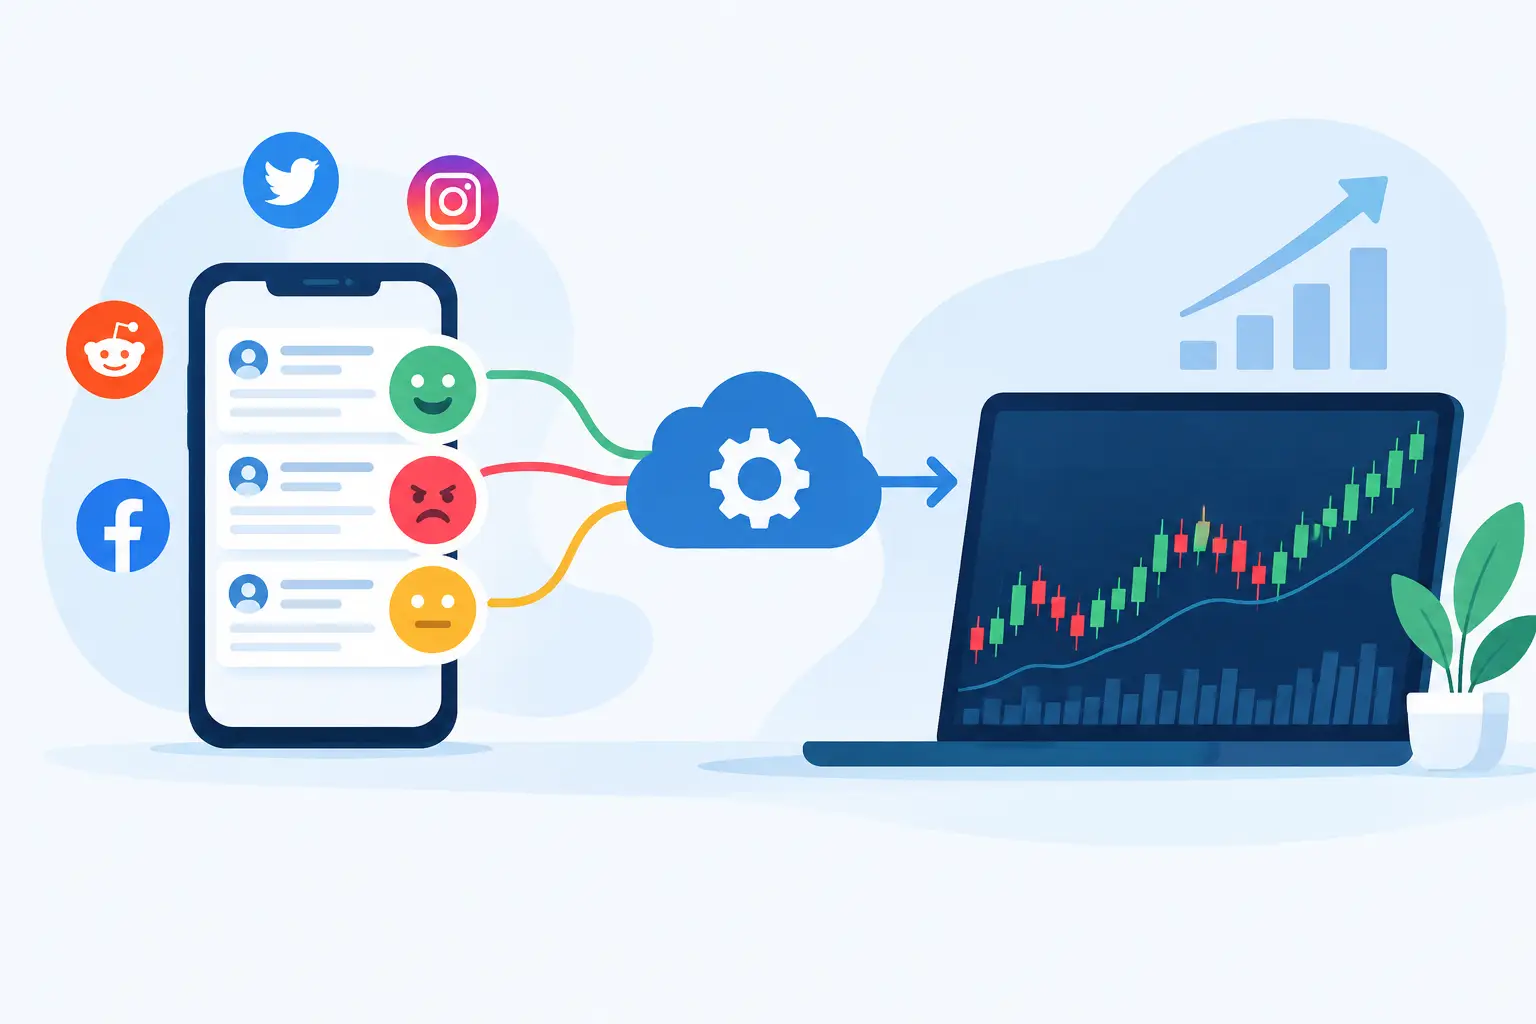
At a minimum, an API should convert unstructured social discussion into ticker-level fields your dashboard, screener, model, or alert engine can use. The baseline fields are mention volume, sentiment score, bullish-to-bearish balance, engagement, and change over time.
But a single sentiment number is rarely enough. A stock with a 0.72 positive score may look compelling until you find that the reading comes from a handful of repetitive posts. A lower score paired with a sharp, sustained jump in unique authors and high-quality engagement may be the more meaningful signal.
The most useful social sentiment stock market API outputs typically include:
- Ticker-level mention counts across defined intervals
- Positive, negative, and neutral sentiment distributions
- Mention velocity and acceleration relative to a baseline
- Unique-author counts to reduce the impact of repetition
- Engagement metrics such as replies, reposts, or reactions
- Topic and keyword extraction to identify the narrative behind the move
- Timestamped source evidence for auditability
These fields turn social activity from a vague market input into data that can be ranked, filtered, and tested.
Sentiment Is a Signal Component, Not a Verdict
Social sentiment works best when treated as one independent input in a broader market process. It can surface emerging attention. It cannot, by itself, determine whether a narrative has durability, whether a catalyst is verified, or whether technical conditions support the move.
That distinction matters because social platforms reward velocity, emotion, and repetition. Those characteristics can produce exceptional early signals around earnings reactions, product developments, regulatory headlines, and sector rotations. They can also create false positives around recycled claims, coordinated posting, and broad market speculation.
A disciplined workflow separates three questions. First: is attention increasing? Second: what is causing it? Third: is market behavior confirming or rejecting the narrative? An API can answer the first question quickly and contribute evidence to the second. News verification and technical context are essential for the third.
This is why independent signal layers matter. When social activity, verified news momentum, and price behavior are blended into one opaque score, it becomes difficult to tell what changed and why. Keeping them distinct gives traders and developers a cleaner basis for screening and model design.
The Metrics That Matter Most
Mention velocity beats raw volume
Raw mention count favors widely followed names. Large-cap tickers can dominate a feed all day without producing a new information edge. Velocity measures the rate of change - for example, mentions in the last 30 minutes versus the stock’s normal level for that time of day.
Acceleration is even more useful. If mention velocity is rising rapidly across multiple intervals, the ticker may be moving from background discussion into an active narrative. That is often more actionable for a screener than a static leaderboard of the day’s most discussed names.
Unique authors expose concentration risk
One account or a tight group can generate a misleading spike. A quality API should distinguish total posts from unique contributors. High mention volume with low author diversity is a warning that the signal may be concentrated. A growing number of independent authors provides stronger evidence that attention is spreading.
This does not mean every broad discussion is meaningful. It means the data has passed an initial quality test: the activity is not simply one message echoed repeatedly.
Sentiment change is often stronger than sentiment level
A stock with consistently positive discussion is not necessarily experiencing a new catalyst. More valuable is the transition from neutral or mixed sentiment to a sustained positive or negative shift, especially when it occurs alongside rising participation.
Build alerts around delta, not only absolute scores. A move from 0.05 to 0.45 may carry more informational value than a stock holding at 0.70 for several days. The same principle applies to negative sentiment. Sudden deterioration in the conversation can signal a changing risk narrative that deserves attention.
Evidence feeds prevent black-box decisions
Every aggregate metric should lead back to evidence. If your system flags a ticker for an unusual sentiment shift, you should be able to inspect the underlying posts, timestamps, authors, extracted themes, and associated news context.
Without this layer, users are forced to trust a score they cannot validate. For systematic research, evidence is also necessary for diagnosing model errors, filtering recurring spam patterns, and understanding why a strategy behaved differently during a specific market event.
How to Integrate the API Into a Market Workflow
The right integration depends on your objective. A discretionary momentum trader may use the API to power a real-time outlier screen. A developer may pull normalized sentiment features into a research database. A portfolio-focused investor may run periodic alerts for conviction changes across a watchlist.
Start by defining the event you want to detect. Avoid the vague goal of finding “positive sentiment.” A more useful definition is: flag stocks where unique-author growth exceeds its 20-day intraday baseline, sentiment improves materially, and the ticker has a fresh verified-news catalyst.
From there, establish a normalized baseline. Comparing every ticker against the same raw threshold creates a bias toward heavily discussed companies. Instead, compare each name against its own typical activity. A 300% increase in discussion can be meaningful for a quiet ticker even if it remains well below the absolute volume of a mega-cap name.
Then apply context filters. You might require a minimum number of unique authors, exclude low-confidence classifications, or suppress events that have already persisted beyond a defined window. These rules reduce duplicate alerts and keep attention focused on emerging changes rather than headlines everyone has already seen.
Finally, store the data. Real-time alerts are useful, but historical records are what make the API operationally valuable. Save sentiment snapshots, velocity readings, topic labels, and alert timestamps. Over time, you can analyze which combinations of variables produced durable market attention, which faded quickly, and where your thresholds need revision.
Common API Design Mistakes
The first mistake is treating every post as equal. Source quality, author behavior, engagement patterns, and duplication all influence whether a mention should carry weight. A basic keyword search will overcount spam, sarcasm, and unrelated references.
The second is ignoring ticker disambiguation. Many ticker symbols overlap with common words, abbreviations, or company names. An API needs entity resolution strong enough to determine whether a post is actually about the listed company. Weak ticker mapping contaminates every downstream metric.
The third is using sentiment labels without confidence. Natural-language classification is probabilistic, especially when posts are short, ironic, or packed with market slang. Confidence values let downstream systems discount uncertain observations instead of treating each label as fact.
The fourth is failing to handle time correctly. Social data moves quickly, and delayed aggregation can erase the advantage of an early signal. Use clear timestamps, consistent market-time conventions, and documented update frequency. For live workflows, minutes matter. For historical research, reproducibility matters just as much.
Building a Better Signal Stack
A social API becomes substantially more valuable when it is connected to verified news and technical data without collapsing those inputs into a single unexplained number. The goal is not to force agreement. Disagreement itself can be informative.
Consider a ticker with rapidly improving social sentiment but no verified-news momentum and weak technical participation. That may represent early speculation, a developing story, or noise. It requires a different response than a ticker where attention, credible news, and market confirmation all rise together.
Sentimentick is designed around this separation. Social chatter, verified news momentum, and technical indicators can be viewed as distinct evidence streams, allowing users to identify what is actually driving the alert rather than relying on an unexplained composite.
For developers, that structure supports cleaner feature engineering. You can test social velocity independently, measure its interaction with news recency, and evaluate whether technical confirmation changes the signal’s persistence. This is more useful than importing one generic sentiment score and hoping it captures the full market narrative.
Data Quality Is the Real Differentiator
Many platforms can return a sentiment label. Fewer can provide a dependable market dataset. The difference comes down to source coverage, ticker mapping, bot and duplication controls, classification confidence, update latency, historical depth, and transparent evidence.
Before adopting an API, test it against known market events. Inspect whether it identified the change early enough to matter, whether the cited conversation matched the actual narrative, and whether its measurements remained stable across quiet and high-volatility periods. Also examine its behavior on obscure tickers, where thin data and ambiguous references expose weak entity resolution.
The objective is not to predict every price move from social posts. It is to reduce the time between a narrative beginning and your ability to investigate it with discipline. A well-designed social sentiment stock market API gives you that speed, while the right filters keep speed from becoming noise.