A ticker can become the center of a market narrative long before that narrative appears in a traditional screener. A cluster of credible headlines, an unusual acceleration in discussion, or a sudden shift from skepticism to conviction can change the research priority in minutes. A real time sentiment analysis api turns that fast-moving information into structured data your workflow can actually use.
For active market participants and developers, the point is not to treat every mention as a signal. The point is to identify when attention is changing, understand what is driving it, and place that information beside price action, volume, and technical context. Speed matters, but evidence matters more.
Why real-time sentiment changes market research
Markets react to expectations, and expectations often shift first in language. Earnings commentary, regulatory developments, product announcements, analyst discussion, and social conversation all create an evolving narrative around a symbol. The challenge is that raw attention is not the same as meaningful attention.
A ticker trending across social platforms may be driven by recycled posts, jokes, low-quality accounts, or broad market speculation. A smaller stream of verified reporting can carry far more informational weight. A useful sentiment system does not simply count mentions. It distinguishes source quality, measures the direction and momentum of the conversation, and preserves the underlying evidence for review.
That distinction matters when monitoring hundreds or thousands of US-listed equities. Manual research works for a watchlist of ten names. It breaks down when the market is repricing themes across sectors, reacting to macro headlines, or rotating attention into unexpected names. An API creates a machine-readable layer between the information firehose and the decisions a trader, analyst, or model needs to make.
What a real time sentiment analysis API should deliver
At a minimum, sentiment data should answer three questions: what is being said, how fast is the conversation changing, and why does the system believe the shift matters? A single positive or negative score cannot answer all three.
A high-quality real time sentiment analysis api should provide ticker-level sentiment with timestamps, source attribution, and a confidence framework. That allows users to separate a persistent change in narrative from a short-lived burst of low-conviction chatter. It also makes the data auditable. When a score moves sharply, you should be able to inspect the news items, posts, or events contributing to that move.
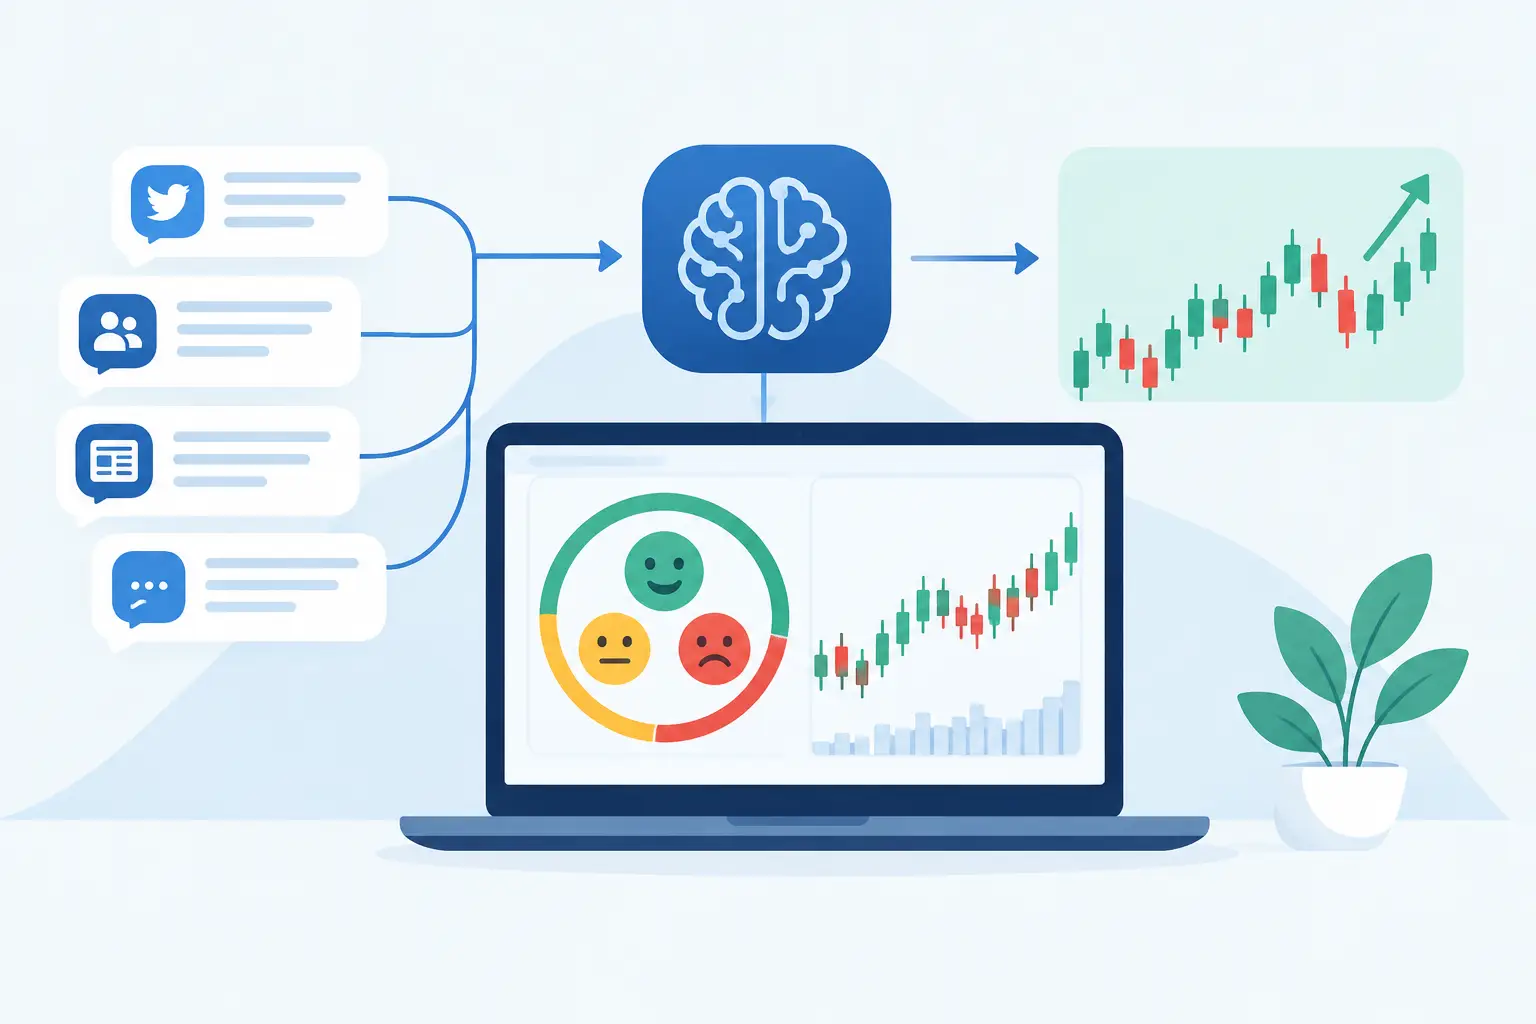
The most useful implementations treat sentiment as several independent signals rather than one opaque number. News momentum can measure changes in verified media coverage. Social sentiment can capture crowd attention and discussion direction. Technical context can show whether the market is confirming, ignoring, or challenging the narrative. Combining these dimensions is more informative than allowing any single feed to dominate the output.
Latency is only useful when the data is clean
Real-time delivery sounds straightforward until source quality enters the picture. Faster ingestion can create more false positives if duplicate articles, bot activity, reposts, and stale content are not controlled. An API that returns a score within seconds but cannot explain the score may add noise instead of edge.
The right latency depends on the workflow. A developer monitoring sudden attention changes may need frequent polling or event-driven alerts. A swing trader running an intraday research process may benefit more from aggregated momentum windows that reduce reaction to isolated posts. Long-horizon investors may focus on sustained narrative change across days or weeks. The best system supports different timeframes without pretending every use case needs the same signal cadence.
Evidence feeds create conviction
Black-box sentiment is difficult to trust, especially when a ticker is moving fast. Transparency changes the workflow. Instead of seeing only that sentiment increased, a user can verify whether the move came from an earnings release, several credible publications, a viral social thread, or a mix of unrelated mentions.
This evidence-first approach helps prevent a common research error: confusing visibility with relevance. A stock can receive intense attention without a meaningful change to its business narrative. Conversely, a relatively quiet but credible stream of reporting can reveal a shift that deserves immediate monitoring. Context gives the score its value.
Build signals around change, not static sentiment
A static sentiment reading is often less useful than the rate of change. A ticker sitting at moderately positive sentiment for several weeks may be less actionable from a research standpoint than one moving rapidly from neutral to positive with accelerating news coverage. The same principle applies in reverse when enthusiasm begins to fade.
That is why sentiment velocity, mention acceleration, and source-weighted momentum belong in a serious market data pipeline. These measures help identify inflection points rather than just popular names. They can also be compared against baselines. Ten positive mentions may be routine for a widely followed large-cap name but highly unusual for a smaller company that normally receives little attention.
A practical model can track the current score, its change across multiple time windows, the volume of unique sources, and the balance between verified news and social discussion. It can then flag deviations from normal behavior. This is more disciplined than treating a raw mention count as proof of market significance.
Sentimentick applies this logic by keeping news, social chatter, and technical indicators independently weighted, with evidence feeds behind the output. That structure gives users a clearer view of whether a narrative has confirmation across multiple dimensions or is being carried by one noisy source.
API workflows that fit real market operations
For developers, the API is most valuable when it fits naturally into an existing research stack. A quant hobbyist may route ticker-level sentiment changes into a custom dashboard and compare them with historical volatility. An independent analyst may create alerts for unusual news momentum in a focused universe. A systematic team may store time-stamped sentiment observations for model testing and post-event review.
The key is to define the event before wiring the data into a workflow. “Positive sentiment” is too broad. A more useful condition might be a rapid increase in source-weighted news sentiment, accompanied by an above-normal volume of unique credible sources and a break from the ticker's normal attention range. That event can be logged, ranked, and reviewed alongside technical behavior.
Alert design deserves the same discipline. Too many low-threshold alerts train users to ignore the system. Too few alerts can conceal early narrative shifts. Start with a narrow universe and clear thresholds, then adjust based on observed false positives and missed events. Alert quality is not measured by how often a notification arrives. It is measured by whether the notification earns attention.
Historical storage is equally important. Real-time feeds are powerful in the moment, but their long-term value comes from evaluation. Record the score, timestamp, source mix, mention velocity, and relevant market context. Over time, this creates a research archive that can reveal which types of sentiment changes were durable, which were noise, and which conditions produced the cleanest signals.
Where sentiment data can mislead
Sentiment is an input, not a verdict. It can lag a breaking event, overstate the importance of a viral topic, or misread sarcasm and ambiguous language. Entity recognition can also create errors when company names overlap with common words, brands, or unrelated entities. Any API provider that presents sentiment as certainty is oversimplifying a probabilistic problem.
Market context matters too. A positive company-specific narrative may have limited effect during a broad risk-off session. A negative headline may be already reflected in price behavior before social discussion catches up. The objective is not to force sentiment to predict every move. It is to use narrative intelligence to prioritize research and detect conditions that deserve closer attention.
Developers should test for these limitations directly. Compare source classes, examine performance across sectors, inspect behavior around high-volatility events, and watch for bias toward heavily discussed names. A model that appears strong in a narrow historical sample may weaken when market regimes change. Transparent inputs make those tests possible.
Turn attention into a research advantage
The market does not reward more noise. It rewards faster recognition of meaningful change. Build your sentiment workflow around verified evidence, rate of change, source quality, and technical confirmation. When a ticker's narrative shifts, the right API should help you see what changed, measure how quickly it is spreading, and decide whether it belongs at the top of your research queue.